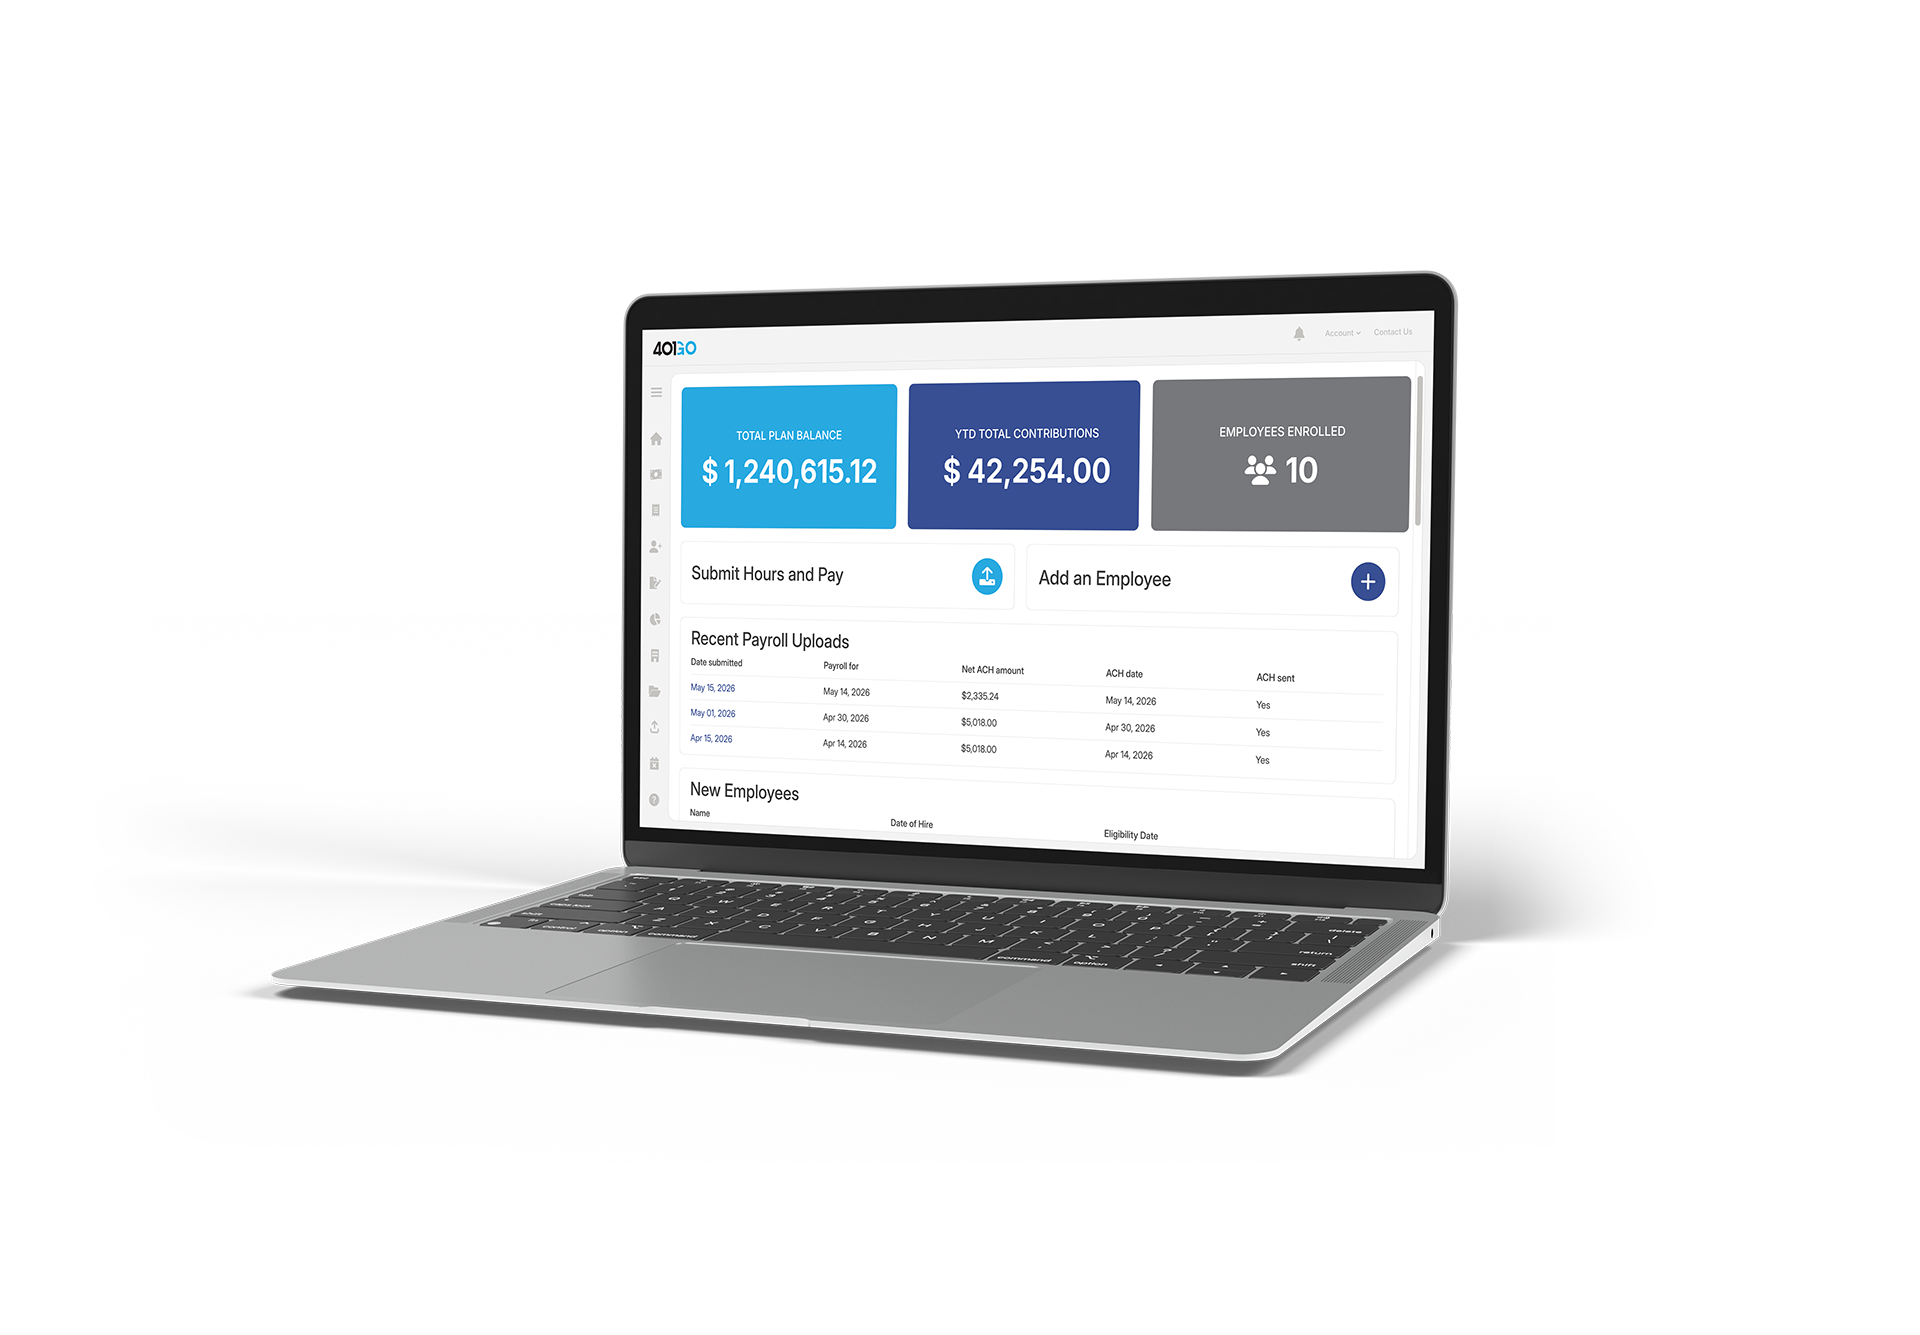
The 401(k) for businesses ready to start – not ready to overthink.
How A Starter 401(k) Works
Think of the Starter 401(k) as the entry point into employer-sponsored retirement. Here’s what makes it different from a Starter 401(k)

No employer contribution required
The Starter 401(k) is a deferral-only plan. Employees contribute directly from their own paychecks, and the employer is not required to provide a company match. This eliminates employer contribution requirements, making plan expenses predictable and manageable for small businesses.

No nondiscrimination testing

Automatic enrollment built in

Contribution limits for 2026
Nearly two-thirds of small business employees still have no access to a workplace retirement plan. A Starter 401(k) changes that today, with zero employer contribution required.

Starting Small Doesn’t Mean Staying Small
The Starter 401(k) is designed as a beginning, not a ceiling. Businesses that start with a Starter 401(k) can upgrade to a standard 401(k) or Safe Harbor 401(k) as they grow — and employees carry their accumulated savings forward.
Questions? We’ve Got Answers.
Who is eligible to offer a Starter 401(k)?
Any employer that doesn’t already sponsor a retirement plan. The Starter 401(k) was created specifically for businesses offering a retirement benefit for the first time. If you already have a 401(k), Safe Harbor, or SIMPLE IRA in place, the Starter 401(k) is not available to you.
Can I contribute as the business owner?
Yes — as an employee of your own business, you can contribute up to $6,000 per year (or $7,000 if you’re 50 or older). However, as the employer, you cannot make additional employer contributions to a Starter 401(k). For owners who want to contribute more — for themselves or their team — a standard 401(k) or Safe Harbor plan unlocks higher limits on both sides.
Does the Starter 401(k) qualify for SECURE 2.0 tax credits?
Yes. Eligible small businesses can take advantage of federal SECURE 2.0 tax credits:
- Startup Administrative Credit: Covers up to 100% of ordinary administrative and setup costs, up to $5,000 per year for the first three years.
- Auto Enrollment Credit: Provides an additional $500 per year for 3 years if you include an eligible auto enrollment feature.
- Employer Match Credit: Additional tax credits of up to $1,000 per employee to help offset employer matching contributions over the first several years.
The Starter 401(k) qualifies for startup administrative and auto enrollment credits, which significantly offset the cost of getting started.
What happens when we’re ready to upgrade to a standard 401(k)?
Is automatic enrollment mandatory?
The Right Plan for Every Client
401GO covers the full range of retirement needs so you can say yes to the right plan for you.
Standard 401(k)
The core offering, built for SMBs
Safe Harbor 401(k)
Simplified compliance for employers who want it
Starter 401(k)
For businesses just getting started
Solo 401(k)
For owner-only businesses
ERISA 403(b)
Purpose-built for tax-exempt organizations
Traditional IRA
Individual retirement access
Cash Balance
For businesses with more complex planning needs
The Hardest Part is Starting. We Made That Part Easy.