Your members built careers with their hands. Help them retire with security.

Benefits That Travel With Your Members
The Right Plan for Every Client
401GO covers the full range of retirement needs so you can say yes to the right plan for you.
Standard 401(k)
The core offering, built for SMBs
Safe Harbor 401(k)
Simplified compliance for employers who want it
Starter 401(k)
For businesses just getting started
Solo 401(k)
For owner-only businesses
ERISA 403(b)
Purpose-built for tax-exempt organizations
Traditional IRA
Individual retirement access
Cash Balance
For businesses with more complex planning needs
Infrastructure for the Organizations That Represent the Trades

Easy for small employers to launch and run
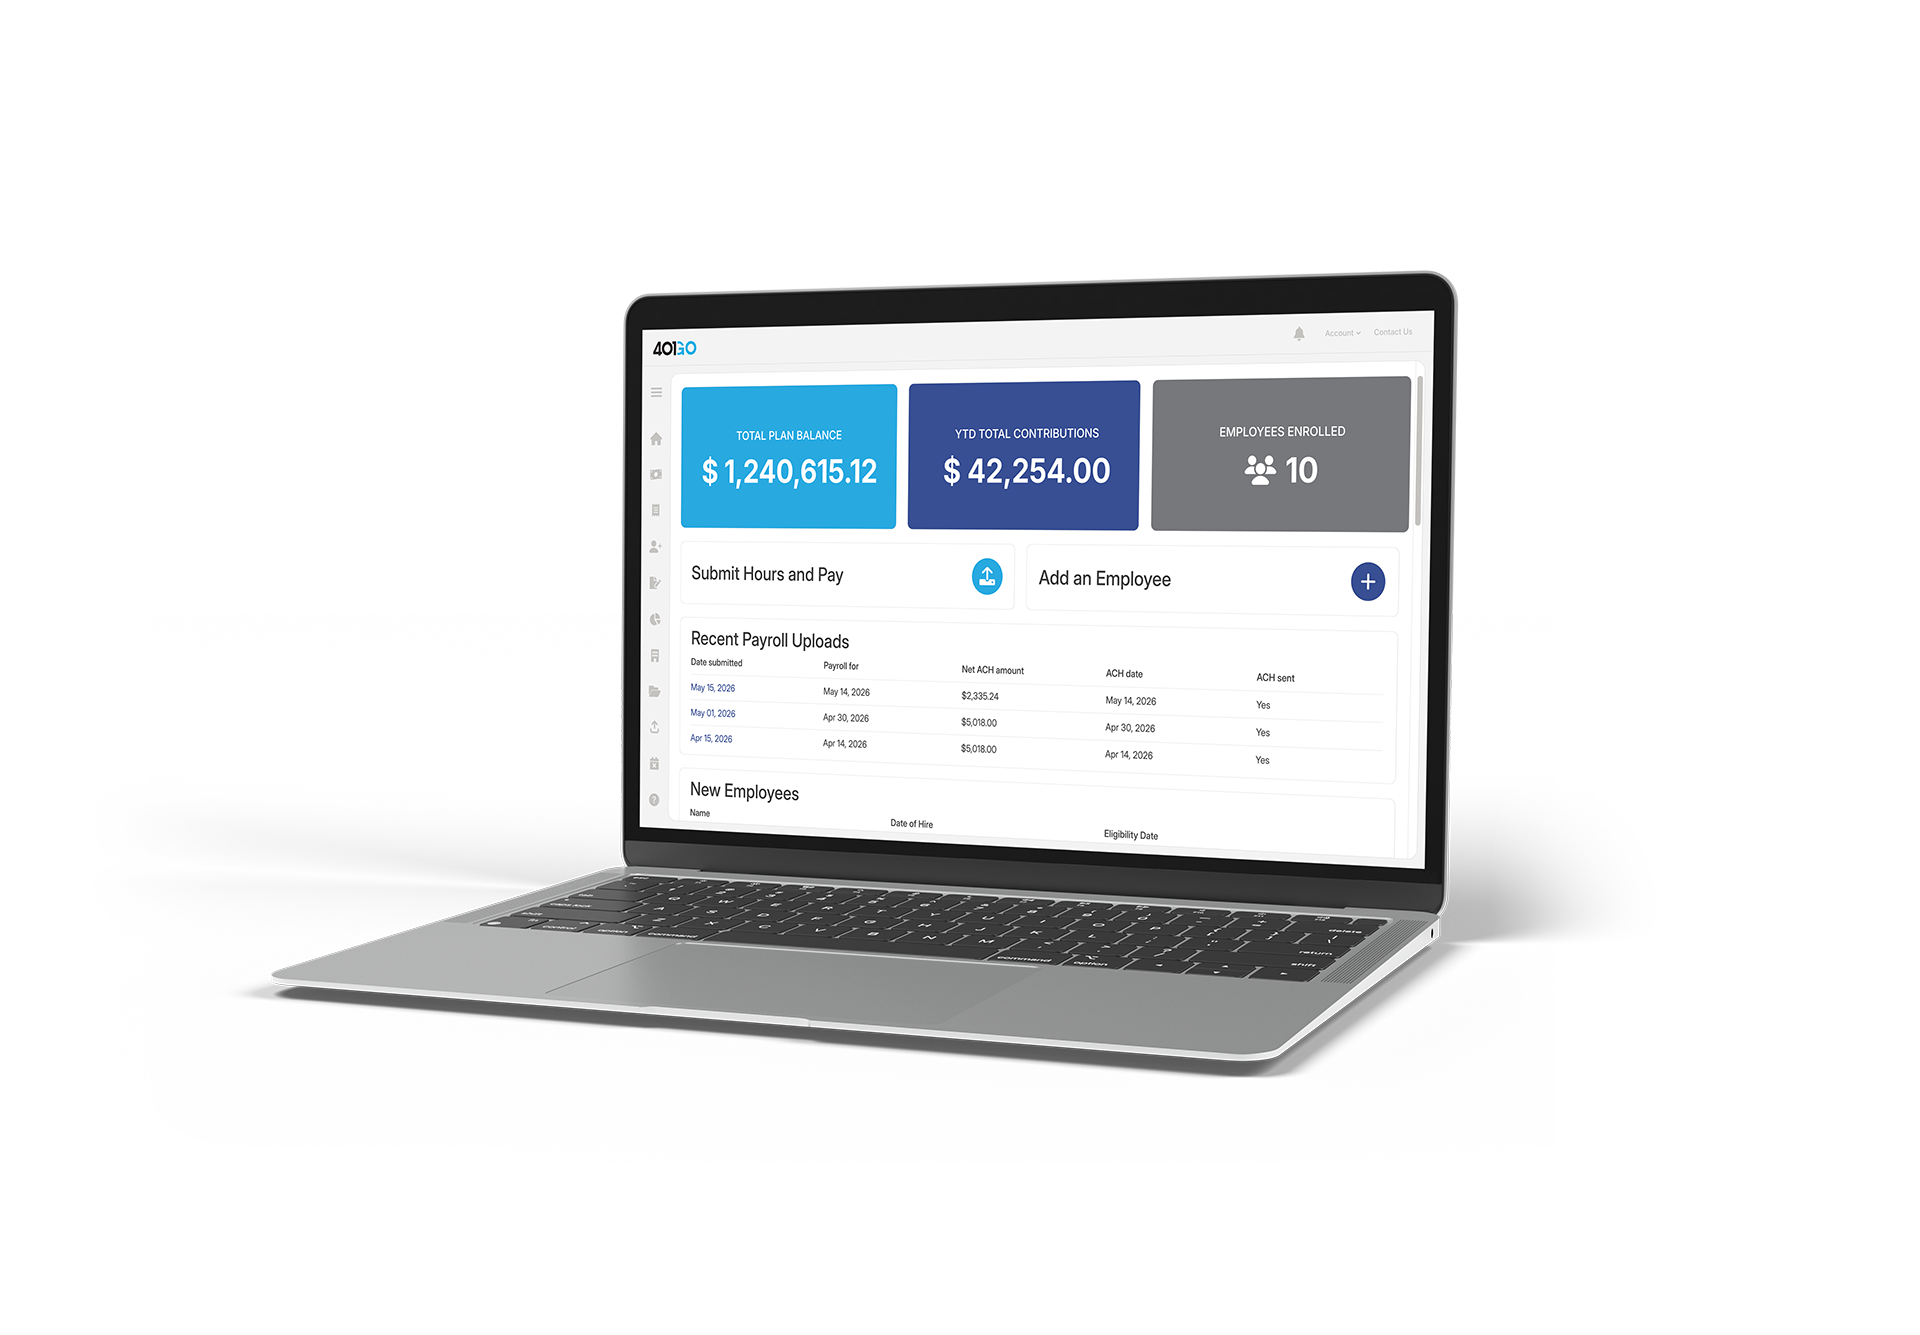
Most of the businesses in your network don’t have HR departments. They’re running lean. 401GO was designed so a business owner can set up a plan in as little as 15 minutes without a consultant and administer it without dedicating significant time to compliance. That’s how you get adoption across your membership.

Native payroll integration

Compliance that runs itself

Tools to drive member engagement

Dedicated human support
Up and running fast. Native payroll integration. Automated compliance. A 401(k) you can actually manage while you build a company.
Your Peers Know the Story
Melissa M, Mid-Market Business Officer
Justin C, Small Business Owner
Jeffery L, Small Business Founder
Will C, Small Business Financial Advisor
Questions? We’ve Got Answers.
Can a trade syndicate or association sponsor a plan for its members?
It depends on the structure — there are multiple ways to approach retirement benefits at the association level, from group plan structures to member employer arrangements. We’ll help you understand what fits your organization’s legal and operational setup and connect you with the right resources. The goal is to make the benefit available to your members in the most workable way possible.
Most of our member employers are small. Is 401GO realistic for them?
What about members who work for multiple employers throughout the year?
What tax incentives exist for small member employers starting a new plan?
The SECURE 2.0 Act provides meaningful federal tax credits for eligible small employers launching new retirement plans. Member employers can take advantage of substantial tax savings across three key areas:
- Startup Administrative Credit: Covers up to 100 percent of ordinary administrative and setup costs, up to $5,000 per year for the first three years.
- Auto Enrollment Credit: Provides an additional $500 per year for 3 years if you include an eligible auto enrollment feature.
- Employer Match Credit: Additional tax credits of up to $1,000 per employee to help offset employer matching contributions over the first several years.
We will help your member employers understand exactly what they qualify for and how these credits significantly reduce initial plan expenses.
From the team.
What’s actually changing in retirement infrastructure, the advisor channel, and the technology underneath it. Written by the people building it, not a content agency.
Ready to Deliver a Retirement Benefit Your Members Actually Deserve?